How to Get a Pay Stub for an Auto Loan: Lender Checklist
Auto lenders ask for pay stubs to confirm income and judge whether the monthly payment fits. Here is what they look for, how many stubs to bring and what to do if you do not have them.
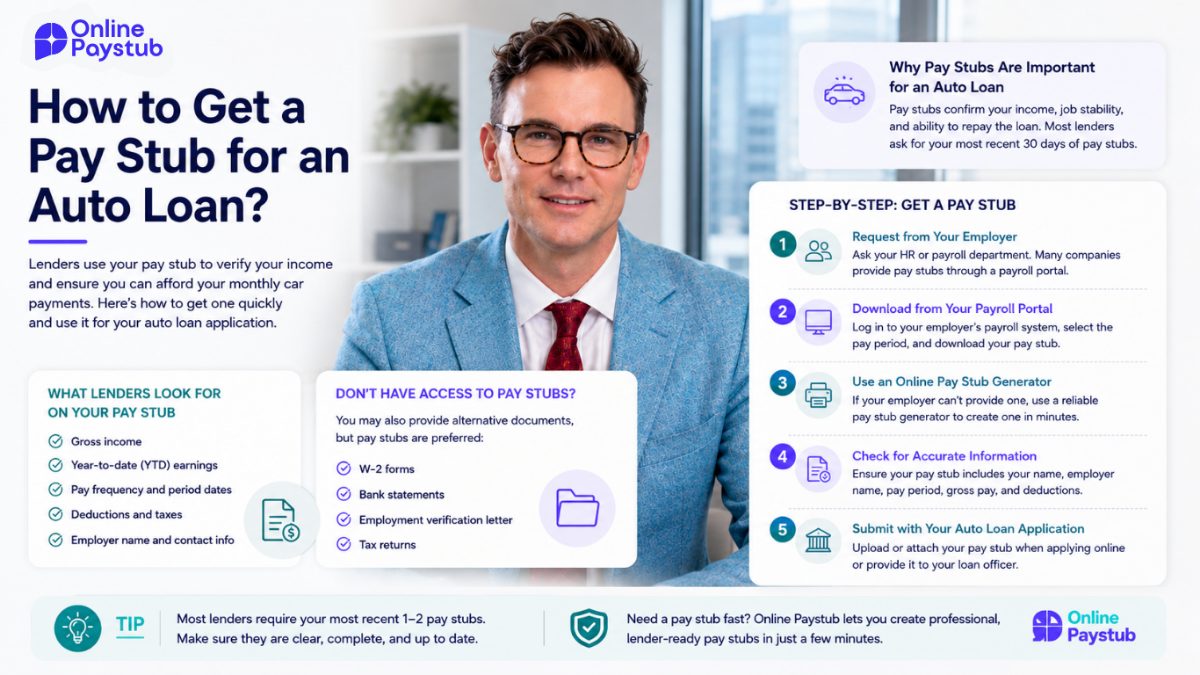
When you apply for a car loan, the lender is answering one question: can this buyer make the payment every month for the next several years? A pay stub is the fastest evidence they have, which is why it is usually the first document requested after the application itself.
Why Lenders Ask for Pay Stubs
A loan application states your income. A pay stub substantiates it. The lender compares the two and uses the verified figure to calculate your debt-to-income ratio: the share of gross monthly income already committed to debt payments. If adding the car payment pushes that ratio past their limit, the application is declined or the loan is restructured, regardless of credit score.
The stub also confirms employment is current. A statement dated six weeks ago raises the question of whether you still work there.
What the Lender Actually Reads
Buyers tend to point at net pay because that is the number they live on. Underwriters look elsewhere:
- Gross pay for the period, since debt-to-income is calculated on gross income.
- Pay frequency, to convert the period amount into a monthly figure.
- Year-to-date earnings, which reveal whether your income is steady or seasonal.
- Employer name and pay dates, to confirm the job is current.
That is also why a stub showing overtime matters. A good month inflates the current period, but the year-to-date column shows the underwriter what you really average.
How Many Stubs to Bring
Two recent stubs is the common request, and some lenders want a full month, which is four stubs on a weekly schedule. Bring more than you think you need. A buyer who hands over a complete set rarely gets asked a second time, and the second request is where financing delays start.
If You Do Not Have Pay Stubs
Self-employed buyers and contractors generally substitute other records: filed tax returns, bank statements showing deposits, 1099 forms and a profit-and-loss statement. These take longer to review, so start the conversation before you are sitting at the dealership.
If you are an employee who simply cannot find recent statements, ask payroll or check the employee portal rather than arriving empty-handed. I walk through the full lender checklist, including what underwriters flag and how to prepare documents in advance, in my complete guide to getting a pay stub for an auto loan for Online Paystub.
A Short Pre-Application Checklist
Before you apply, confirm you can produce the last two stubs, that your name and employer are correct on them, and that the year-to-date figure matches what you reported on the application. Those three checks resolve most income-verification problems before they happen.